Manchester City’s rule-breaking may go beyond football. The independent Commission found that the club inflated its income, concealed expenses and paid a key individual through a sham consultancy. Leaked documents identify him as City’s manager, Roberto Mancini, with payments routed to his company, Sparkleglow Holdings Ltd. We believe the evidence points to £12m in unpaid UK tax. The consequences could include a much larger tax bill and a criminal investigation.
This report is subject to four important caveats.
First, our analysis assumes that the Commission’s findings of fact are correct. City maintains its innocence and says it will appeal, alleging material errors of law, principle and fact (but not identifying any of them).
Second, we have only the heavily redacted, 40-page core decision. The detailed appendices remain unpublished. They are likely substantial: the parties’ document index alone ran to 750 pages.
Third, we rely on documents obtained by Der Spiegel as part of the Football Leaks investigation, and on the original 2018 reporting by Der Spiegel and L’Espresso, also covered by The Guardian. We have reviewed the underlying materials ourselves and assume the documents are authentic; to our knowledge, this has never been questioned.
Four, we make no claims that any named individuals committed tax evasion or other criminal offences; the facts suggest that they may have done, but this will depend on their state of mind at the time.
This report is therefore a preliminary assessment based on the evidence currently available. We conclude:
Roberto Mancini received large payments under a consultancy contract with Al Jazira Sports and Cultural Club.
On the basis of the Commission’s findings and leaked documents, the contract was a sham, and in reality represented remuneration for Mr Mancini’s employment with Manchester City.
Manchester City should therefore have applied UK PAYE income tax and National Insurance in the usual way – but the evidence suggests the club unlawfully failed to do so. We expect around £12m of tax went unpaid.
We don’t know whether HMRC has commenced an investigation into these arrangements and, if it has, whether it has been resolved – but there’s no sign of any settlement payments in Manchester City’s accounts.
The highly irregular nature of the arrangement, and the Commission’s findings of sham and intentional concealment, suggest to us that there should be a criminal investigation into whether tax evasion offences were committed.
The Commission’s finding that Manchester City knowingly filed false accounts suggest that Companies Act criminal offences may have been committed.
The decision
The independent Commission’s published decision describes two separate ways in which Manchester City manipulated its finances. The point was to circumvent, and indeed break, the rules limiting how much clubs can spend relative to their income.
First, Manchester City inflated its income. The club recorded funding from its owner, Abu Dhabi United Group (ADUG), as sponsorship revenue, which boosted City’s reported income by more than £830m across the 2009/10 to 2017/18 seasons.
Second, it hid its expenses. The club’s accounts omitted costs which were really City’s, but which ADUG paid. These omitted payments understated expenses by £8.866m, £7.4m and £500,000 for three individuals. There was a complex related arrangement involving players’ image rights and an entity called Fordham.
As the decision puts it:
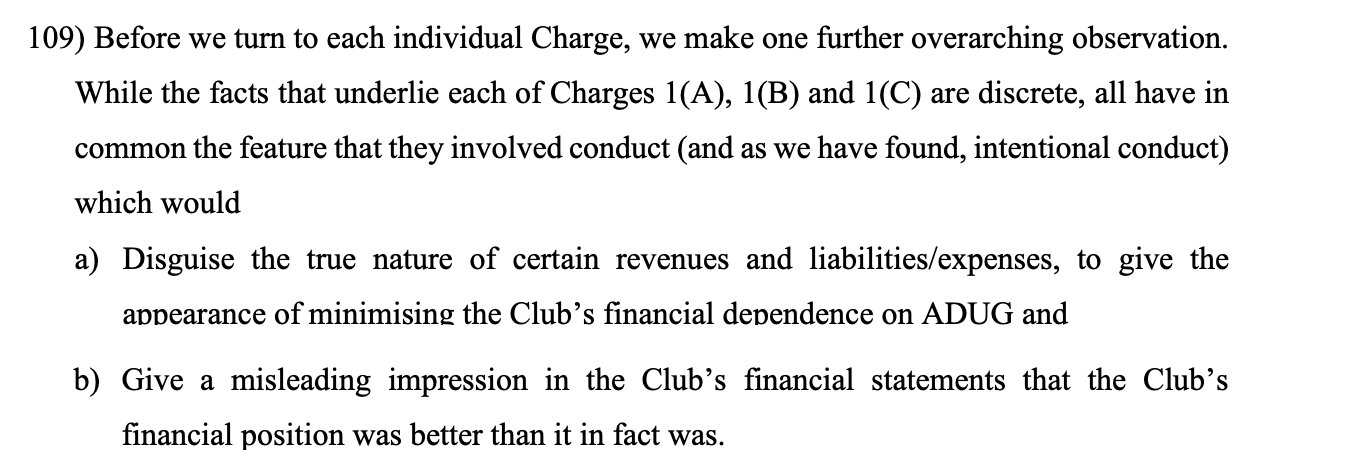
This report focuses mainly on the payments to the first of those individuals. The other hidden payments may raise similar issues, but we have less information about them. We also talk about the general criminal law implications of filing false accounts.
The wider inflation of income probably doesn’t have adverse tax consequences for City, although not enough information is available at the moment to say that with any confidence. Conversely, whilst it’s sometimes suggested the deception means that City overpaid corporation tax or VAT, our preliminary view (on the limited information available) is that this is probably not the case. Certainly they can’t have overpaid corporation tax, because their losses meant they paid no corporation tax over this period:
The arrangement with Roberto Mancini
The decision describes an arrangement under which remuneration for services contracted to be provided to City by an individual was instead recorded in a consultancy agreement between the individual and another party, funded by £8.866m from ADUG. The description is heavily redacted:
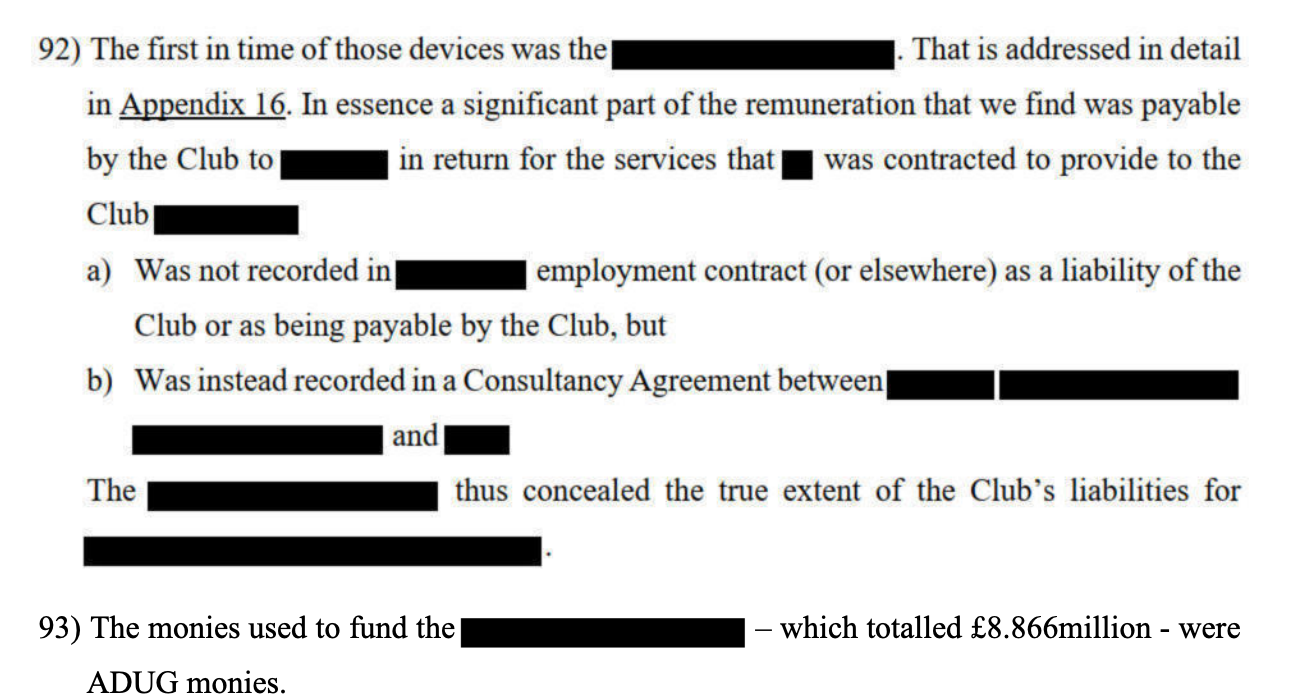
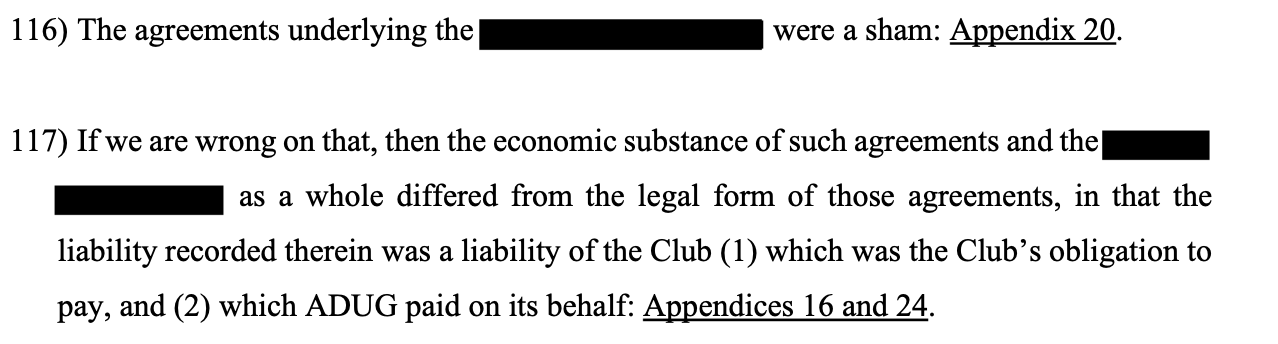
The decision then says that the contractual agreements were a sham but that, if the decision is wrong on that, City was the entity obliged to make the payments under the agreements, and ADUG made them on City’s behalf. The terms should have been included in the individual’s contract with City.
The name of the individual (and even their gender) is redacted.
Previous reports have said it was Roberto Mancini (and more on those reports below). We can, however, be reasonably confident it was Mr Mancini without needing to rely on these reports. Take a look at the description in the decision of the rules that were breached:
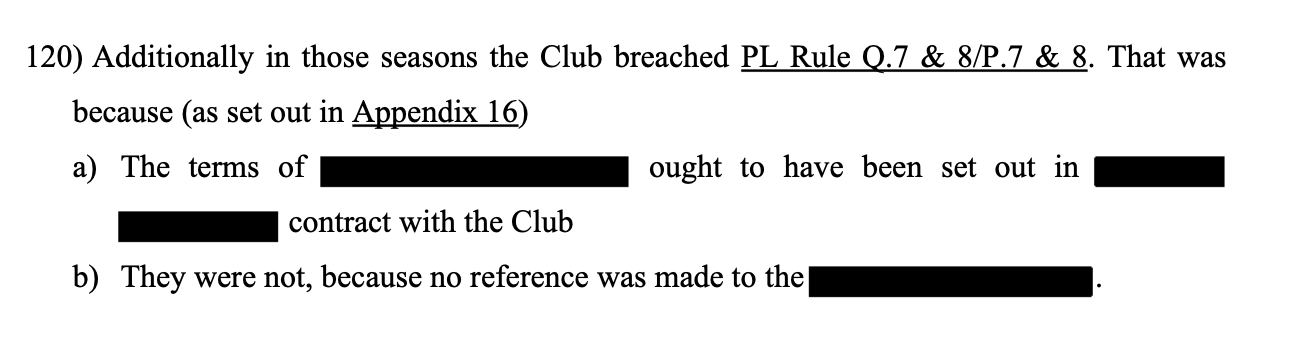
PL Rules Q.7/P.7 and Q.8/P.8 relate to manager contracts of employment, so this arrangement definitely related to a manager. There were four managers during the period in question (2009/10 to 2017/18): Pep Guardiola, Mark Hughes, Roberto Mancini and Manuel Pellegrini (plus Brian Kidd, caretaker for the last two games of 2012/13). But the decision says in paragraph 118 that the arrangement related to four seasons. Only one of those managers served for four seasons in this period: Mr Mancini.
We can double-check by looking at the length of the redacted text. For example, in this paragraph:
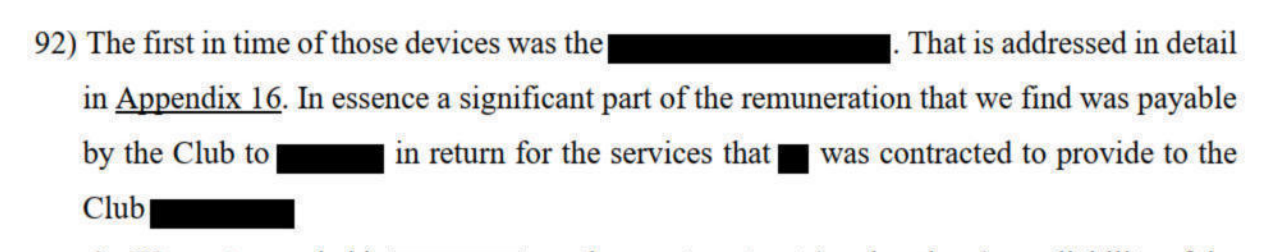
We measured the black box after “payable by the Club to” as 40.3 points wide. “Mancini” in the same font (12pt Times New Roman) would be 40.0 points wide. The names of the other managers during this period are either too small (“Hughes”, 36.7 points) or too large (“Pellegrini”, 46.7 points, and “Guardiola”, 48.0 points).
The Commission’s findings are also consistent with the facts and chronology revealed by documents leaked in 2018, which name Mr Mancini throughout.
The chronology
The “Football Leaks” revealed a 53-page bundle of documents relating to Mr Mancini. Neither Mr Mancini nor Manchester City has disputed the authenticity of these documents. They are also consistent with the findings in the Commission’s decision, and, critically, the payments listed in the bundle add up to the £8,866,367 figure used in the decision.
If we discard the possibility that the bundle is forged, we are confident that it is describing the same arrangement that is the subject of the Commission’s decision.
Here’s the initial chronology revealed from the bundle, most of which was previously reported by Der Spiegel and L’Espresso:
19 December 2009: Manchester City signs an agreement in principle (a “heads of agreement“) with Mr Mancini giving him a basic salary of £1,450,000 per season on a net basis, after deduction of tax. This kind of “net-of-tax” salary would be extraordinary in most of the business world, but is the norm in football: the club bears the tax.
Also 19 December 2009: Al Jazira Sports and Cultural Club sends Mr Mancini heads of agreement for a “Consulting Agreement” (pp.5-6). Al Jazira would pay Mr Mancini’s company (unspecified) a fee of £1,750,000 per year for coaching services in Abu Dhabi, for “a minimum of [4] days per Year”. The fees “will be paid without deduction of any taxation”. Al Jazira is, like Manchester City, owned by Sheikh Mansoor.
March 2010: The consultancy agreement is finalised (see pages 7-17). It’s signed between Al Jazira and Sparkleglow Holdings Ltd, a Mauritian company, for four days each year. The commencement date is 1 January 2010, and the fee is £1.75m a year plus a “Signing On Fee” of £62,328.77.
It’s hard to explain why Mr Mancini would receive more money from a four day consultancy contract than from his main employer. Harder still to explain the strange signing-on fee. But perhaps because the 1 January commencement date for the consultancy agreement is 13 days after Mr Mancini was appointed as manager at City, and £1,750,000 × 13/365 = £62,328.77?
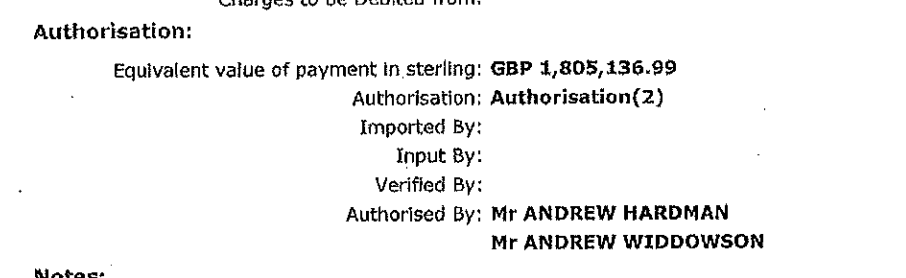
Things became clearer when, on 25 March 2011, Sparkleglow asked Al Jazira to pay the first £1,805,136.99.
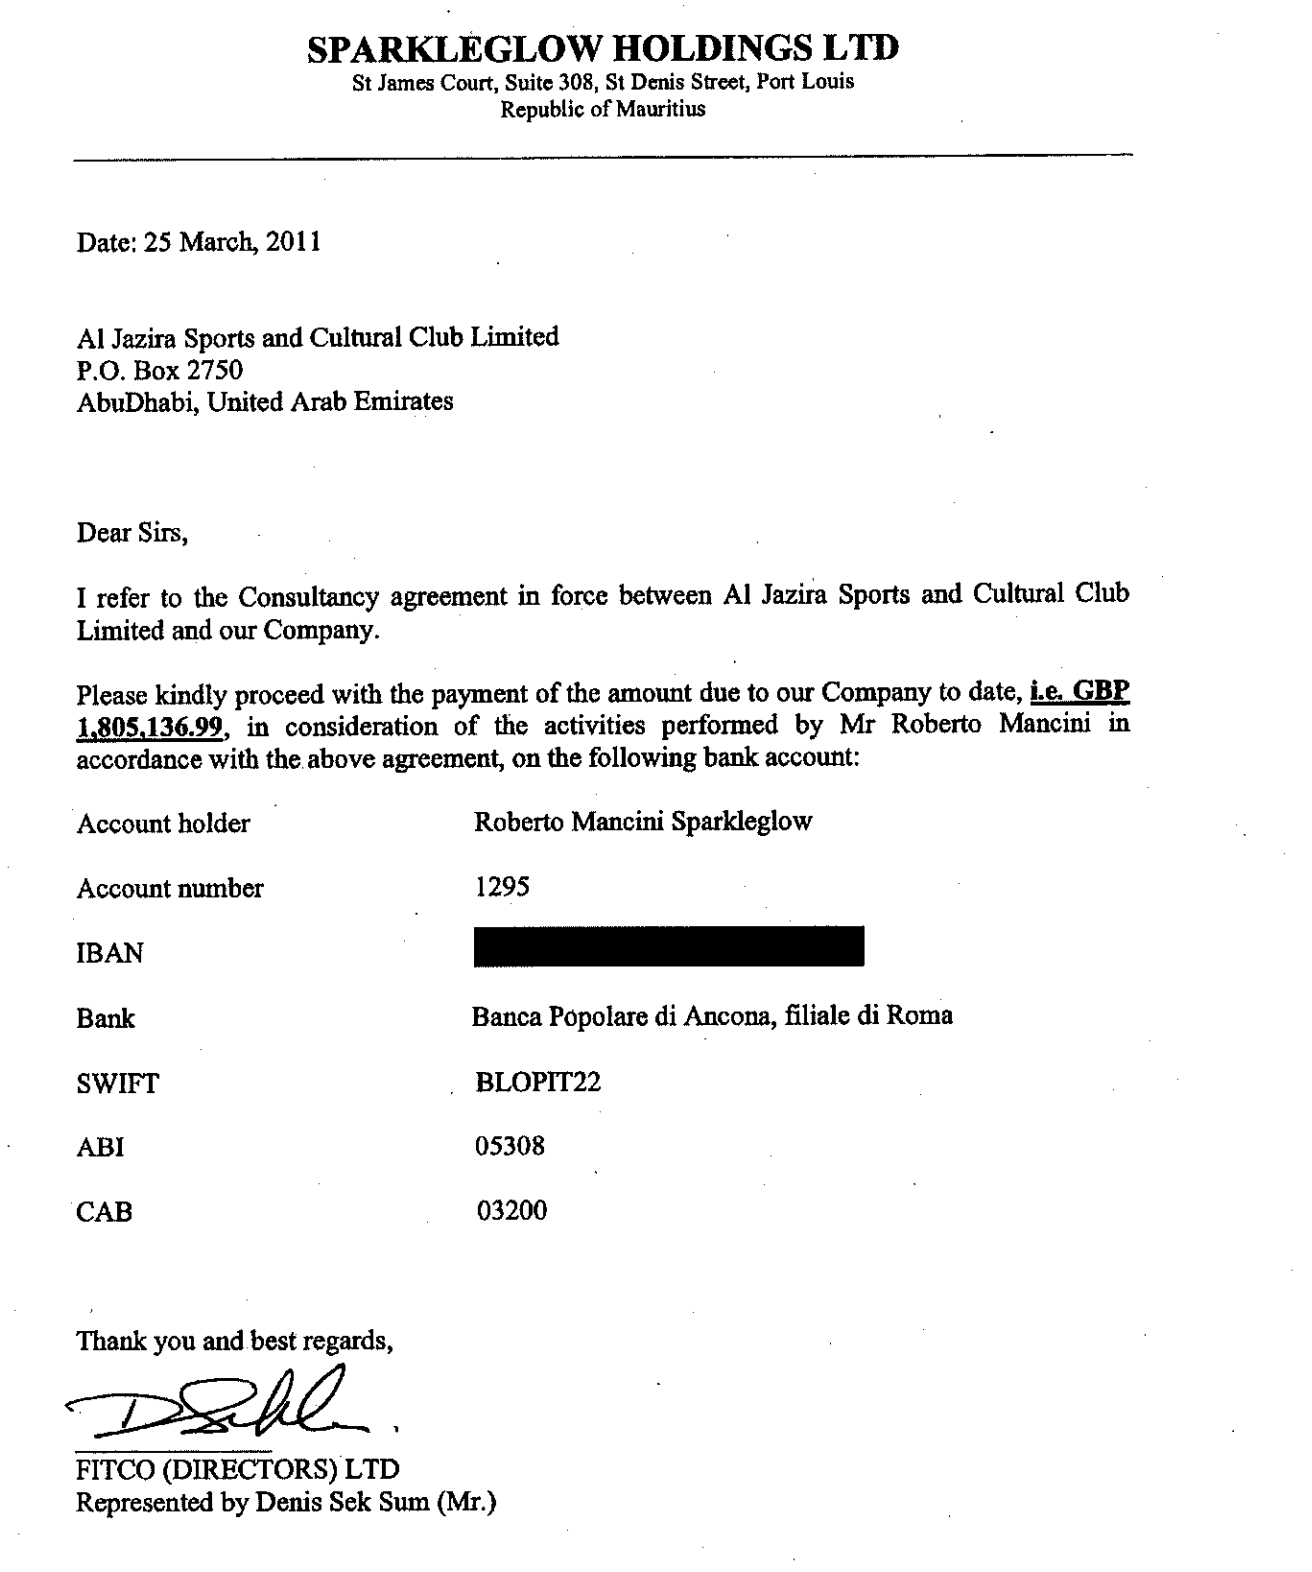
This exact amount is paid, but not by Al Jazira:
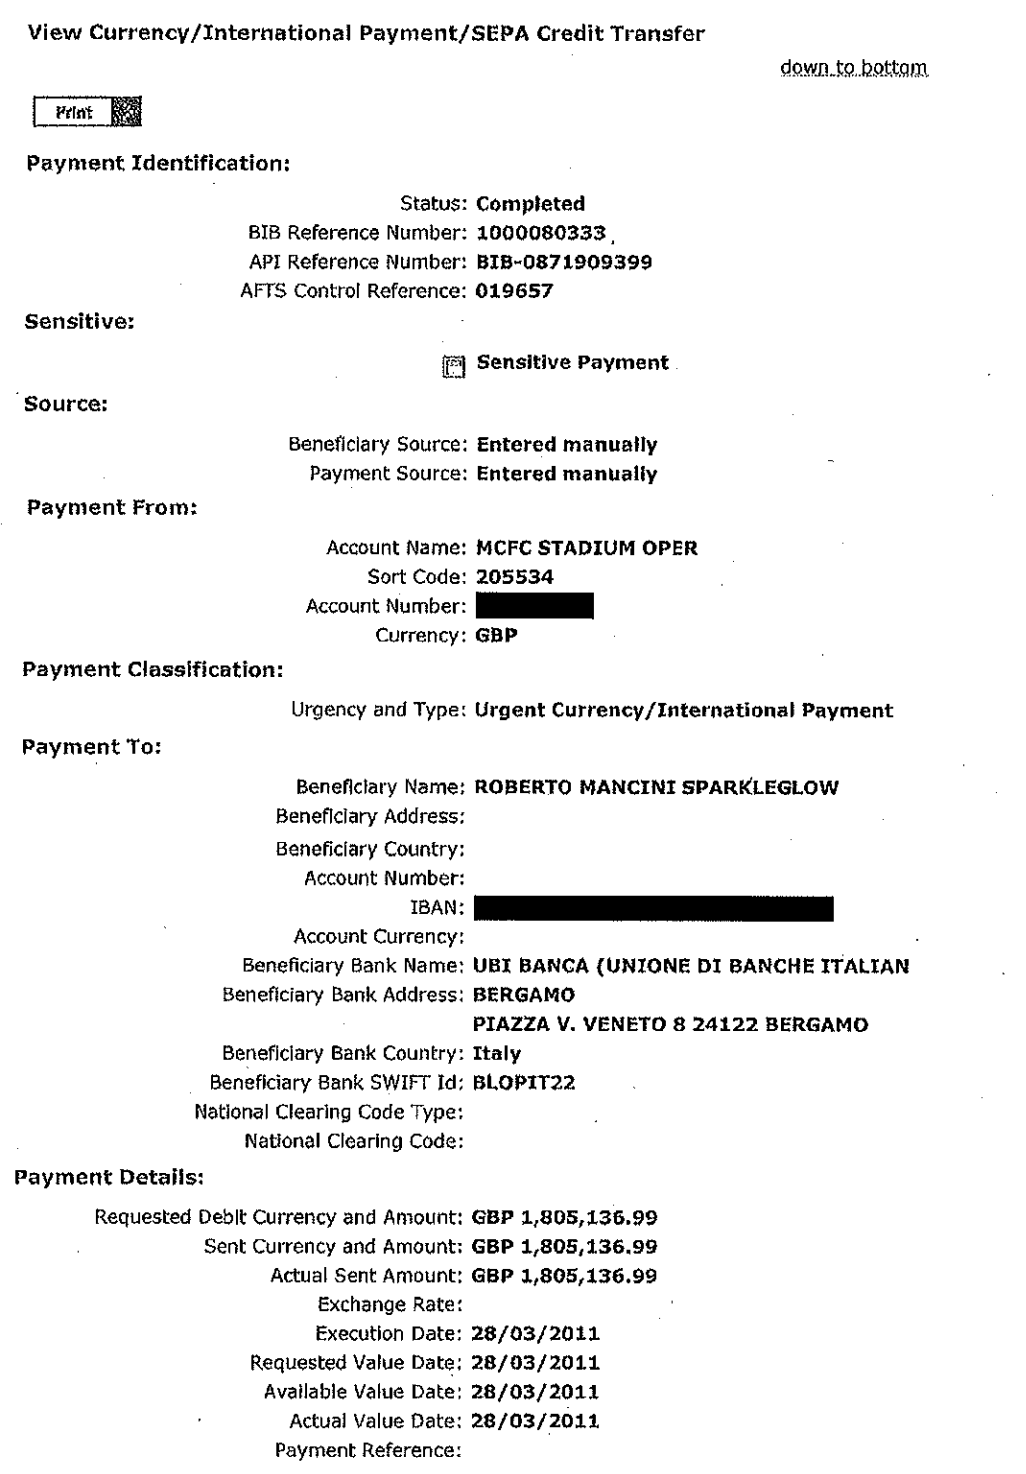
The payment was made from an account with Barclays Bank Manchester called “MCFC Stadium Oper” and authorised by the head of finance at Manchester City:
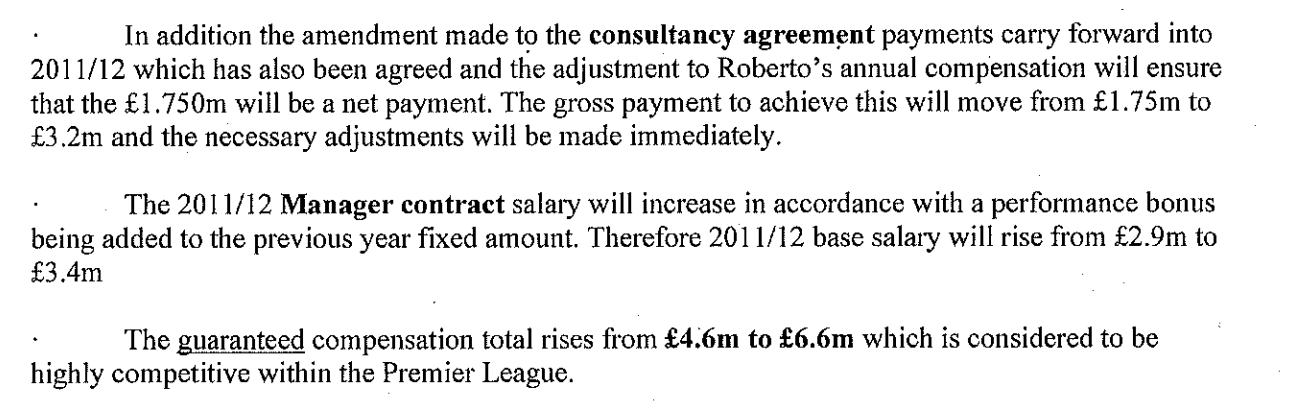
Then, when Mr Mancini’s lawyer sought to renegotiate elements of the consultancy contract, she did not write to Al Jazira. She wrote to City’s chief executive, Garry Cook.
Manchester City, of course, was not a party to the consultancy contract. But Mr Cook nevertheless agrees to make an additional payment to cover Mr Mancini’s Italian tax, and says explicitly that this was all part of Mr Mancini’s overall compensation:
The arrangement changed in July 2011 (possibly for Italian tax reasons). The Sparkleglow consultancy agreement was terminated with effect from 31 March 2011 and replaced by a new consultancy agreement between Al Jazira and Italy International Services srl (pages 30-39), a Rome company at the address of Mr Mancini’s lawyers.
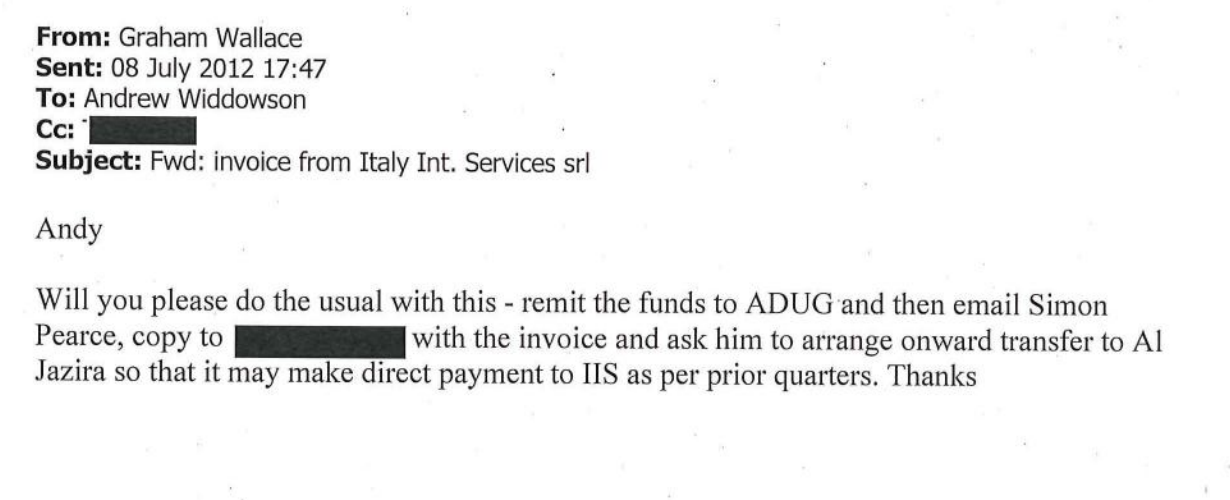
There then seems to have been some attempt to hide what was going on. When payments were made, the Italian company sent invoices to Al Jazira. Then City paid ADUG, ADUG sent the money to Al Jazira, and Al Jazira paid the Italian company.
This all became routine. Here’s City’s chief operating officer asking the head of finance to arrange the payments.
So it is not at all surprising that the Commission’s decision says this was a “sham” or, failing that, ADUG acting on behalf of Manchester City:
On the evidence of the leaked documents, this is one of the clearest cases of sham our team has seen.
Should Manchester City have paid tax on Mr Mancini’s consultancy income?
Mr Mancini was, we assume, fully taxed on his income under his main contract with Manchester City. The club will have applied PAYE to deduct income tax and employee National Insurance from his wages, and paid employer National Insurance on his gross wages.
The position for Mr Mancini’s consultancy agreement should have been the same.
You can’t magically make a salary untaxed by calling it a consultancy fee. If the payments were really for Mr Mancini’s work at Manchester City, they were employment earnings and should have been taxed accordingly.
The law looks at what a payment is for, not just what the contract calls it. Taxable “earnings” include salary, wages and “anything else that constitutes an emolument of the employment”. That’s deliberately broad. A payment can be employment income even if it comes from someone other than the employer.
National Insurance is a separate charge. Remuneration derived from employment generally falls within the Class 1 rules, creating both employee and employer liabilities. Again, changing the label or diverting the payment through another party won’t change the result.
So it doesn’t matter who made the payment under the consultancy agreement, or which person/company received it. It was Mr Mancini’s earnings, and the club should have put it through payroll.
There should therefore have been UK tax. Manchester City should have applied PAYE and National Insurance to its payments to Mr Mancini under the consultancy agreement in exactly the same way as under his main employment contract.
This is not an obscure or finely balanced point. On the facts found by the Commission, we would expect the tax treatment to be obvious to any experienced tax adviser, even one who is not a remuneration tax specialist.
Did Manchester City pay the tax?
It seems likely that it did not, and the club unlawfully failed to account to HMRC for the PAYE income tax and National Insurance.
We say that for several reasons.
First, we can infer it from the absence of any discussion of UK tax in the discussion of the consultancy agreement in the leaked correspondence, which is very focussed on Italian tax. UK tax is mentioned only in the context of Mr Mancini’s “normal” wages from City.
Second, the correspondence talks about Italian tax being paid by Mr Mancini at 45.1%. There is a double tax treaty between the UK and Italy which means that, where someone is employed by a UK company and carrying on employment in the UK, the UK always has the right to tax their employment income.
So Manchester City should have been applying UK income tax and National Insurance. It’s possible Mr Mancini also had some Italian tax liability (e.g. if he was resident in Italy for some of the years in question), and in principle he could credit UK tax against that, but UK tax should have been the main consideration. The correspondence shows that it wasn’t even discussed – they were proceeding as if this was a real consultancy between Mr Mancini and Al Jazira when the parties surely knew that it wasn’t. The consequence was that they paid Italian tax but no UK tax.
If you like this article, consider subscribing to our free newsletter
No spam or advertising. Cancel anytime.
Not interestedAlready subscribed
As an aside, the Italian tax was about £1m a year cheaper than the UK tax that should have been paid. Because Mr Mancini’s deal was “net”, this was City’s saving, not Mr Mancini’s.
We doubt anyone at City ever made this comparison. The original arrangement, with a Mauritian company and fees paid “without any deduction or withholding whatsoever in respect of any taxation“, looks as if it was intended to result in no tax anywhere. Italian tax only appears in the documents in mid-2011, when Mr Mancini’s lawyer asked for “a compensation for the higher taxes to be paid”. So Italian tax was probably a late addition, not a choice.
Third, if City had accounted for UK tax in the usual way, it would have undone the pretence. PAYE only applies to an employee’s pay. Operating it would have been an admission that the consultancy fees were really Mr Mancini’s salary from City. The payments would then have had to appear in City’s accounts as staff costs, which is exactly what the arrangement was designed to avoid.
Fourth, we asked Manchester City’s press office if it could confirm that PAYE and National Insurance were correctly paid:
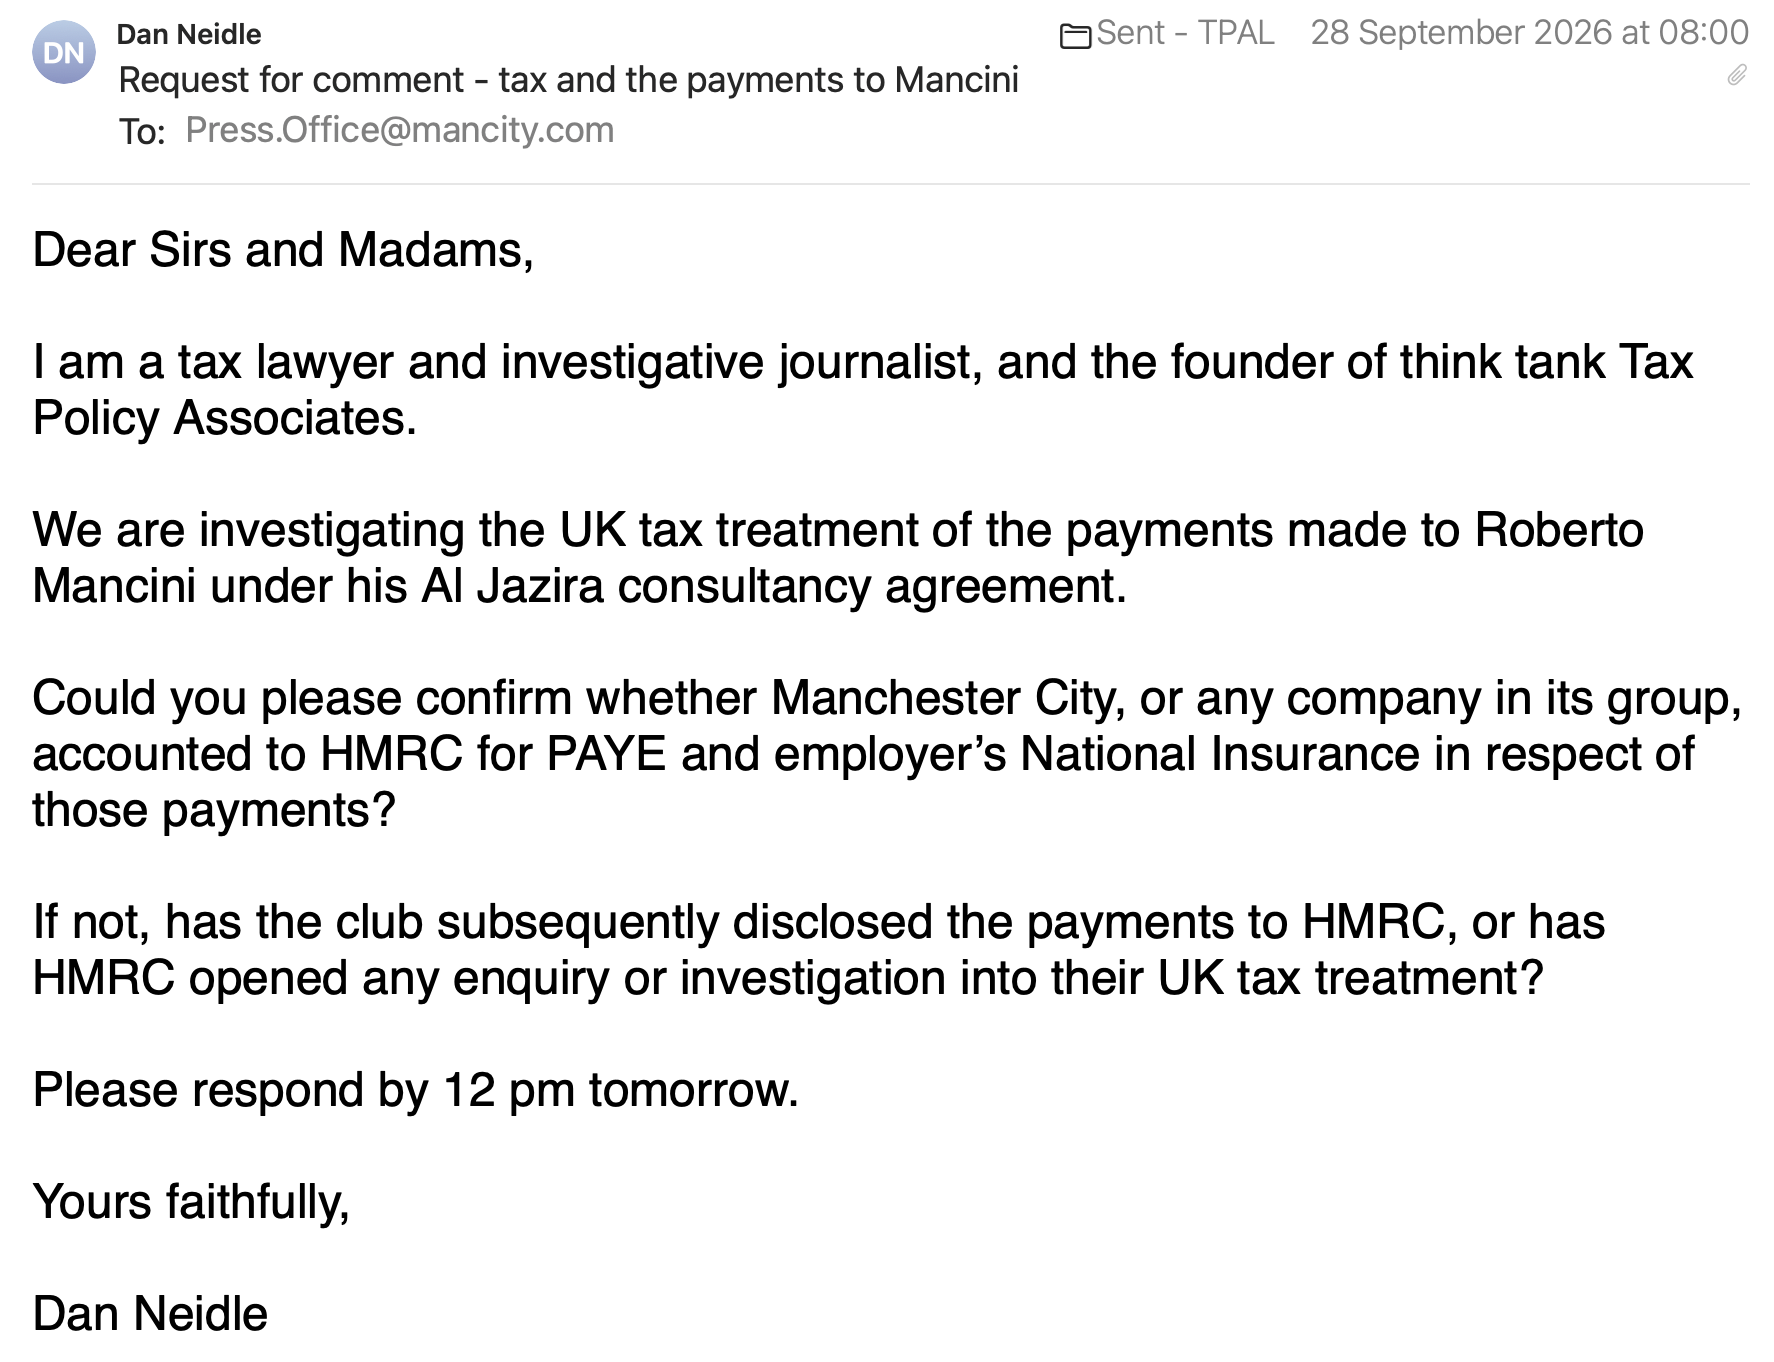
This should be a very easy question. We didn’t receive a reply.
We sent a follow-up…
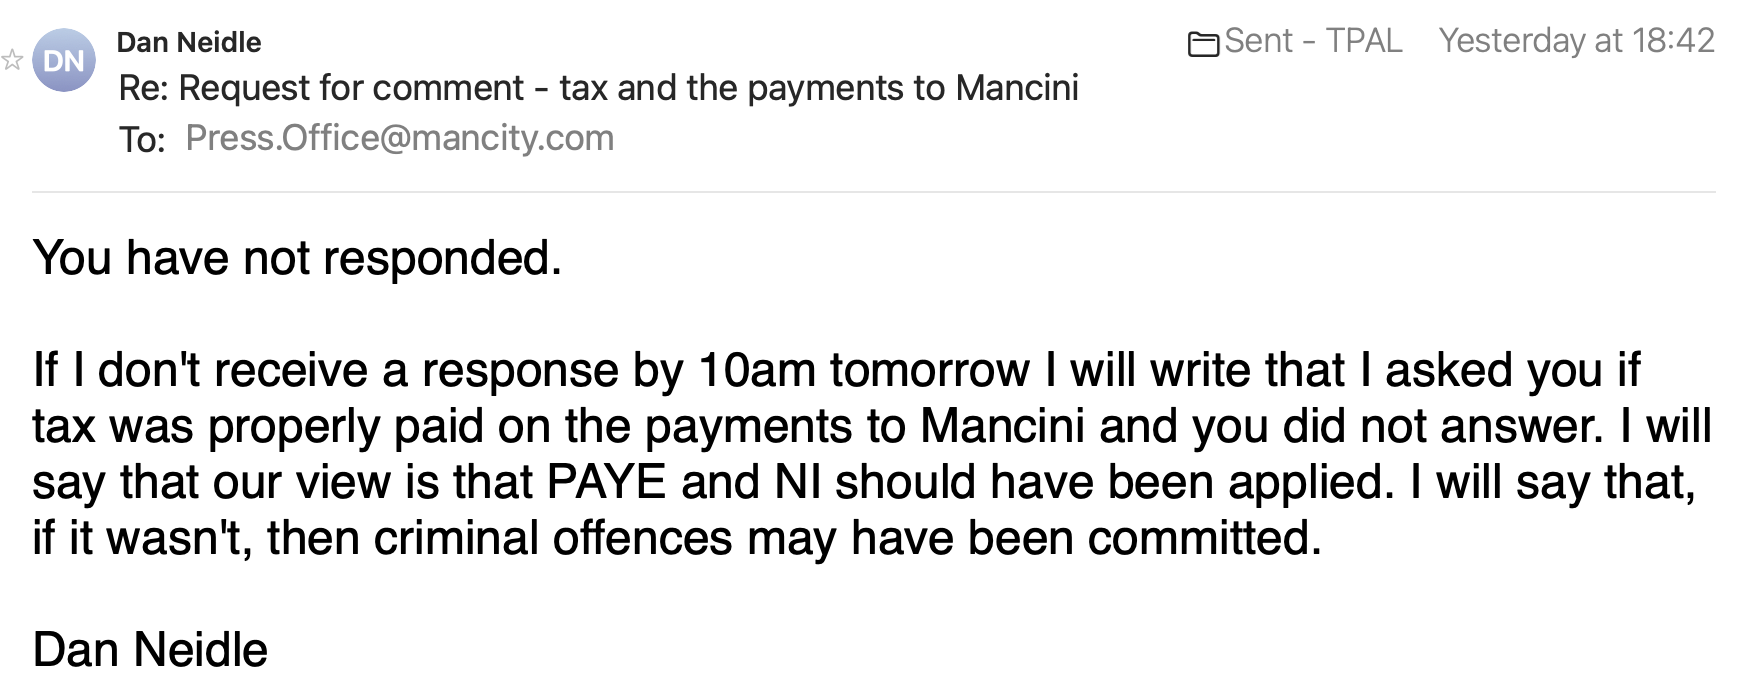
… and again received no reply.
In our experience it is highly unusual for someone to not comment, or even respond, when we inform them we are reporting on whether they committed a criminal offence.
The consequences
When Der Spiegel published in November 2018, HMRC said it would be “relentless in pursuing” any club that had tried to avoid tax and that it was visiting every Premier League club, while declining to comment on identifiable taxpayers. Nothing has been reported since. We reviewed Manchester City’s accounts from 2018 to 2024/25, and none contain a quantified provision for tax on Mr Mancini’s contract, and the forensic accountants we work with haven’t been able to identify any sign of such a payment.
We would be surprised if HMRC hadn’t opened an enquiry at some point after 2018; it will have been well in time to do that.
That enquiry could have been resolved in Manchester City’s favour (although that seems unlikely on the facts available to us). It could have ended with Manchester City paying the tax, but we see no sign of that in the club’s accounts.
So it is possible that the enquiry is ongoing, and eight years is not an unusual timeframe for a complex enquiry.
If the tax wasn’t paid at the time and it still hasn’t been paid today, but HMRC opened an enquiry within the time limits, then this is our estimate of the total amount that is due. It works out as considerably more than the figure would have been if City had simply complied with the law at the time – that’s an effect of paying people a “net of tax” amount:
Tax on £8.87m paid to Mr ManciniIncome tax and NIC£11.6mInterest to date£7.0mPenalty at 35% to 50%£4.1m to £5.8mTotal£23m to £24m
One might think this is an unfair result because the club has already paid the Italian tax, and now UK tax is being paid too. The flippant answer is that you should expect unfair results when you play these sorts of games. The technical answer is that if the position had been rectified earlier, then Mr Mancini could, in principle, have recovered some of the Italian tax, but it is now too late.
In principle, Mr Mancini himself would be liable, but in most cases HMRC looks to recover the tax from the employer.
Was this tax evasion?
Unpaid tax and tax evasion are not the same thing.
Tax evasion involves a deliberate and dishonest attempt to evade tax, not merely an error or an unsuccessful legal argument. It’s most commonly prosecuted as the common-law offence of cheating the public revenue, but there are specific statutory offences as well.
Let’s assume, as seems likely, that Manchester City should have applied PAYE and National Insurance to Mr Mancini’s consultancy payments, but didn’t. Why didn’t it? And does this rise to the level of a criminal offence?
The crucial legal question to determine whether a tax evasion offence was committed is whether the relevant personnel at City were “dishonest”. Under English law, this means asking whether their conduct was dishonest by the standards of ordinary decent people (regardless of whether the individuals themselves believed at the time that they were being dishonest).
The usual defence people raise to a tax evasion prosecution is that they made a mistake, or they honestly thought what they were doing was correct.
The failure to deduct any UK tax from the consultancy agreement payments doesn’t look like a simple mistake; it seems to have been anticipated from the start. After all, the agreement said the fees “will be paid without deduction of any taxation”. But the relevant City personnel might say that they believed the Al Jazira consultancy was a real and separate arrangement, genuinely referable to activity in Abu Dhabi, so that no UK tax was due. Yes, they got the tax wrong, and City owes the tax, interest and penalties, but they acted in good faith.
A defence like that is, however, hard to square with the leaked documents. City’s chief executive described the consultancy fee as part of Mr Mancini’s “guaranteed compensation”. City’s head of finance authorised the first payments out of City’s own bank account. After that, City’s finance team routinely sent the money to ADUG, for ADUG to send to Al Jazira, for Al Jazira to pay Mr Mancini’s company. And the Commission has found that the agreements were a sham (albeit to the civil and not criminal standard; and the Commission was not a jury).
Alternatively, they could accept that the consultancy agreement was a sham, designed to fool the Premier League, but say they had no idea that tax was due. Here it would be relevant to ask whether they obtained outside advice. If they did, and they followed that advice, then any prosecution would be challenging. If there was no tax advice on an arrangement this unusual then that raises its own questions.
Ultimately, whether to believe such a defence, and whether to find that the individuals were dishonest, would be for a jury to decide in light of all the facts: the tax reporting, the underlying communications and other evidence of the relevant individuals’ knowledge and intentions.
We should add that we are not suggesting that any specific individuals at Manchester City, or indeed Mr Mancini, committed an offence. We do not know. We are saying that there appear to be good grounds for a criminal investigation of the circumstances under which a sham arrangement was put in place and tax was not paid when it should have been.
Are there other criminal offences?
This report focuses on Mr Mancini’s consultancy arrangement, but the facts set out in the decision suggest that the police should be looking at whether non-tax offences were committed.
False accounting
Section 17 of the Theft Act 1968 makes it an offence dishonestly to falsify accounting documents, with a view to gain for oneself or another, or an intention to cause loss to another.
The Commission found the accounts materially misstated income and expenses: paragraph 101. It found intentional concealment (paragraph 109) and that City knew the accounts did not give a true and fair view, or alternatively was reckless about that (paragraph 114).
Again, the crucial legal question to determine whether an offence was committed is whether the relevant personnel at City were “dishonest” (see the discussion above).
However, there is an additional challenge for a false accounting prosecution: did Manchester City’s personnel act with a “view to gain”? Manchester City may have ultimately been looking to make a gain from its cheating, but in the short term, its actions lost money rather than made it.
Approving accounts which do not comply with the law
Section 393 of the Companies Act 2006 requires directors to be satisfied that accounts give a true and fair view before approving them. Under section 414(4), a director can commit an offence where non-compliant accounts are approved, the director knew of or was reckless about the non-compliance, and failed to take reasonable steps to secure compliance or prevent approval.
There’s also a specific company law offence that could apply: the accounts were then filed with Companies House, and it’s an offence to knowingly or recklessly deliver materially misleading, false or deceptive documents to Companies House.
The Commission found that nine seasons’ financial statements failed to give a true and fair view (paragraph 101) and that this was intentional (paragraph 114). That was, of course, to the civil rather than criminal standard, but on the face of it, there seems a strong case that a prosecution should be considered.
Misleading the auditors
Under section 501(1) of the Companies Act, knowingly or recklessly giving an auditor a materially misleading, false or deceptive statement can be an offence where it concerns information or explanations the auditor required, or was entitled to require.
The Commission says that even City’s auditors remained unaware of the disguised funding scheme (see footnote 7 to paragraph 68). It also describes documents generated to conceal the true arrangements from regulators and auditors (see paragraph 78).
Again, there seems a strong case for a criminal investigation here, subject again to the point that the decision was to the civil and not the criminal standard.
We are, once more, not saying that any particular individuals committed an offence. We do not know. We are saying there appear to be strong grounds for a criminal investigation.
Many thanks to M, K and P for their remuneration tax analysis, A, S and O for additional comments, and thanks to L for criminal law advice.
Thanks most of all to Der Spiegel and L’Espresso for their original 2018 reporting.
Disclosure: Manchester City is being represented by law firm Clifford Chance LLP. Our founder, Dan Neidle, was a senior partner at Clifford Chance until 2022. When he was a partner, he had no involvement in or knowledge of the case, and has at no time spoken to anyone at the firm regarding it.
Photo by Mylo Kaye on Unsplash.